How to Start a Micro Lending Business in Kenya (2026 Guide)

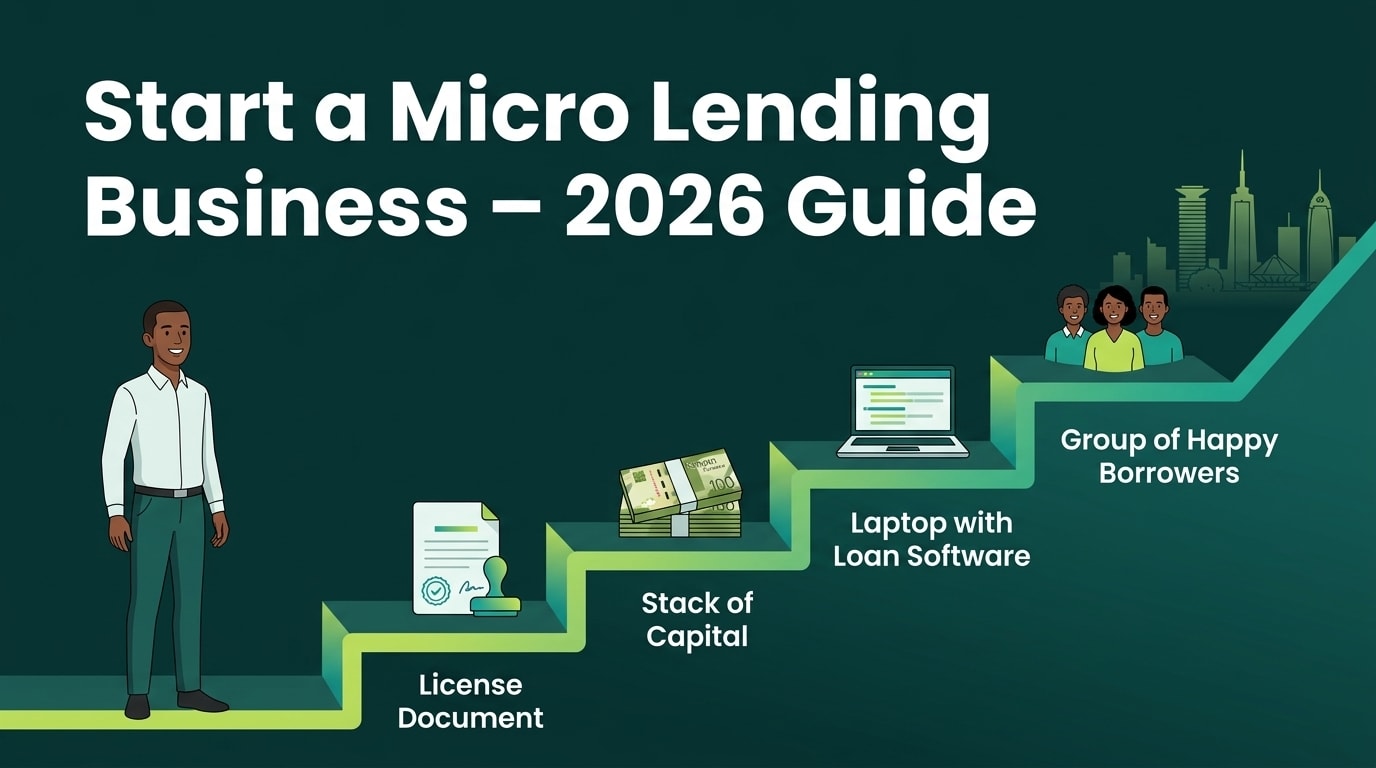
Micro lending is one of the most common small businesses people start in Kenya. Demand is constant: traders need stock money, workers need cash before payday, and parents need school fees in January. But a lending business is easy to start and easy to lose money in. The difference between a profitable loan book and a pile of unrecoverable debts is usually decided before the first loan goes out.
This guide walks through how to start a micro lending business in Kenya in 2026. It covers the legal requirements under CBK's new rules, how much money you need, how to design your loans, the systems to set up and how to keep defaults under control.
Step 1: Make sure you can lend legally
Since the Business Laws (Amendment) Act, 2024, anyone running a non-deposit-taking credit business needs CBK approval. That means lending your own money without taking deposits, whether through an app, USSD or an office. The Non-Deposit-Taking Credit Providers Regulations published on 29 September 2026 set two routes:
- Registration: for smaller lenders. KES 100,000 to apply, then KES 250,000 a year.
- Licence: for lenders starting with KES 20 million or more in capital, and for registered lenders whose capital, borrowings or loan book passes KES 20 million. KES 100,000 to apply, then KES 500,000 a year.
Lending without approval is an offence. Kenyan courts have also held that unlicensed lenders cannot legally enforce their loans, so you may be unable to recover the money you lend. Read our full guide: how to get a CBK lending licence in Kenya.
Want to take deposits? Then you are not a micro lender. You need to be a SACCO (regulated by SASRA or the Commissioner for Co-operative Development) or a microfinance bank licensed by CBK under the Microfinance Act, both with much higher requirements.
Step 2: Choose your niche and lending model
Successful micro lenders specialise. Pick a borrower group you understand and can reach cheaply:
| Model | Typical borrower | Loan shape | Main risk |
|---|---|---|---|
| Trader and business loans | Market traders, shops, boda boda riders | Weekly installments over 4–12 weeks | Irregular income |
| Salary advance and check-off | Employees of a partner employer | One payment on payday, or monthly | Job loss, employer dependency |
| Group loans | Chamas and self-help groups | Weekly or monthly, with group guarantee | Group breakdown |
| Asset and logbook loans | Vehicle or asset owners | Monthly, secured by collateral | Collateral valuation and recovery |
| Digital (app or USSD) loans | Mobile users at scale | Small, short loans, often a single payment | High default rates and fraud. Needs strong data. |
Step 3: Work out how much money you need
Your budget has three parts:
- Setup and regulatory costs: company registration, CBK's KES 100,000 application fee and first annual fee, legal help with your policies, and data protection registration where required.
- Operating costs: staff, loan management software, SMS, M-Pesa charges, office and marketing.
- Lending capital: the money you actually lend. This is the largest part, and the part most beginners underestimate.
As an example of the running costs, loan management software such as Lendpoint costs KES 5,000 a month, plus a one-time KES 10,000 onboarding fee. That includes M-Pesa disbursement and collection, SMS reminders and USSD.
Step 4: Understand the numbers before you lend
Defaults matter far more than interest rates. Consider KES 1,000,000 lent in four-week loans with a flat charge of 10%:
| Default rate | Interest earned | Principal lost | Result per cycle |
|---|---|---|---|
| 0% | KES 100,000 | KES 0 | +KES 100,000 |
| 5% | KES 95,000 | KES 50,000 | +KES 45,000 |
| 10% | KES 90,000 | KES 100,000 | −KES 10,000 |
At a 10% default rate, before paying a single shilling of rent or salaries, you are already losing money. Your credit policy and collections matter more than anything else in the business.
Step 5: Write your credit policy and loan products
CBK expects a written credit policy, and you need one anyway. Decide:
- Who qualifies: ID, KYC, income evidence, guarantors or collateral, and a CRB check.
- How much they can borrow: start new borrowers small and raise limits only after on-time repayment.
- Pricing: interest (flat or reducing balance), processing and other fees, and the total cost of credit. All of it must be disclosed to the borrower before they borrow, and changes need CBK approval and 30 days' notice to borrowers.
- Repayment: weekly, bi-weekly or monthly installments matched to how your borrowers earn.
- Arrears: grace period, penalties, restructuring and when a loan is escalated. See how to design penalties and grace periods.
Step 6: Set up your systems
A spreadsheet and a business phone are how most lenders start, and they are why many lose track of their money. Before your first loan, set up:
- An M-Pesa Paybill registered to your company, with access to Safaricom's Daraja API so disbursements and repayments can be automated.
- A loan management system that holds every borrower, loan and payment in one ledger. It should calculate interest and schedules, send loans to M-Pesa, match repayments automatically and flag arrears on day one. See how M-Pesa repayment automation works.
- SMS with a branded Sender ID for disbursement confirmations and reminders.
- A CRB subscription to check borrowers before you lend.
CBK also asks for a description of your ICT system when you apply, so choosing it early helps your application too.
Step 7: Launch small, measure everything
Start with a small number of borrowers and track three numbers weekly:
- PAR1: the share of the portfolio with any overdue installment, your earliest warning.
- PAR30: loans more than 30 days late, your main health measure.
- Collection rate: amount collected against amount due this week.
Grow only when these numbers are stable. Our guide on how to cut NPLs in microfinance explains each lever in detail.
Common mistakes new lenders make
- Lending before being approved by CBK, and then being unable to enforce repayment.
- Growing too fast: large first loans to unknown borrowers.
- Lending to friends and family under softer rules than everyone else.
- Reconciling M-Pesa by hand, so arrears are found weeks late.
- Applying penalties inconsistently, which teaches borrowers that due dates are negotiable.
- Mixing business and personal money in one M-Pesa line.
Ready to set up your loan book properly from day one? See how Lendpoint works for new lenders or start a 7-day free trial.
Frequently asked questions
Do I need a licence to start a money lending business in Kenya?
Yes. Under the CBK Act as amended in 2024 and the 2026 Non-Deposit-Taking Credit Providers Regulations, you need CBK registration (for smaller lenders) or a licence (from KES 20 million in capital), whether you lend digitally or from an office.
How much capital do I need to start micro lending in Kenya?
You need enough for CBK's KES 100,000 application fee and the first annual fee (KES 250,000 for registration), setup and running costs, and your lending capital, which is the largest part. Lenders with KES 20 million or more in capital need a full licence.
Is micro lending profitable in Kenya?
It can be, but profit depends far more on defaults than on interest rates. With a 10% charge per cycle, a 10% default rate already wipes out your margin before operating costs. Strict credit limits and fast collections are what make it profitable.
What interest rate can a micro lender charge in Kenya?
Kenya's interest rate cap was repealed in 2019, but non-deposit-taking credit providers must have their pricing parameters approved by CBK. They must disclose the full cost of credit, including the APR, before lending, and get CBK approval before changing rates.
Can I run a lending business with just M-Pesa?
You can disburse and collect through M-Pesa, but use a Paybill registered to your company rather than a personal line. Pair it with a loan management system that matches every payment to the right loan automatically.
What is the difference between a micro lender and a microfinance bank?
A micro lender lends its own money and does not take deposits, so it is registered or licensed by CBK as a non-deposit-taking credit provider. A microfinance bank also takes deposits from the public and is licensed under the Microfinance Act, with much higher capital and regulatory requirements.